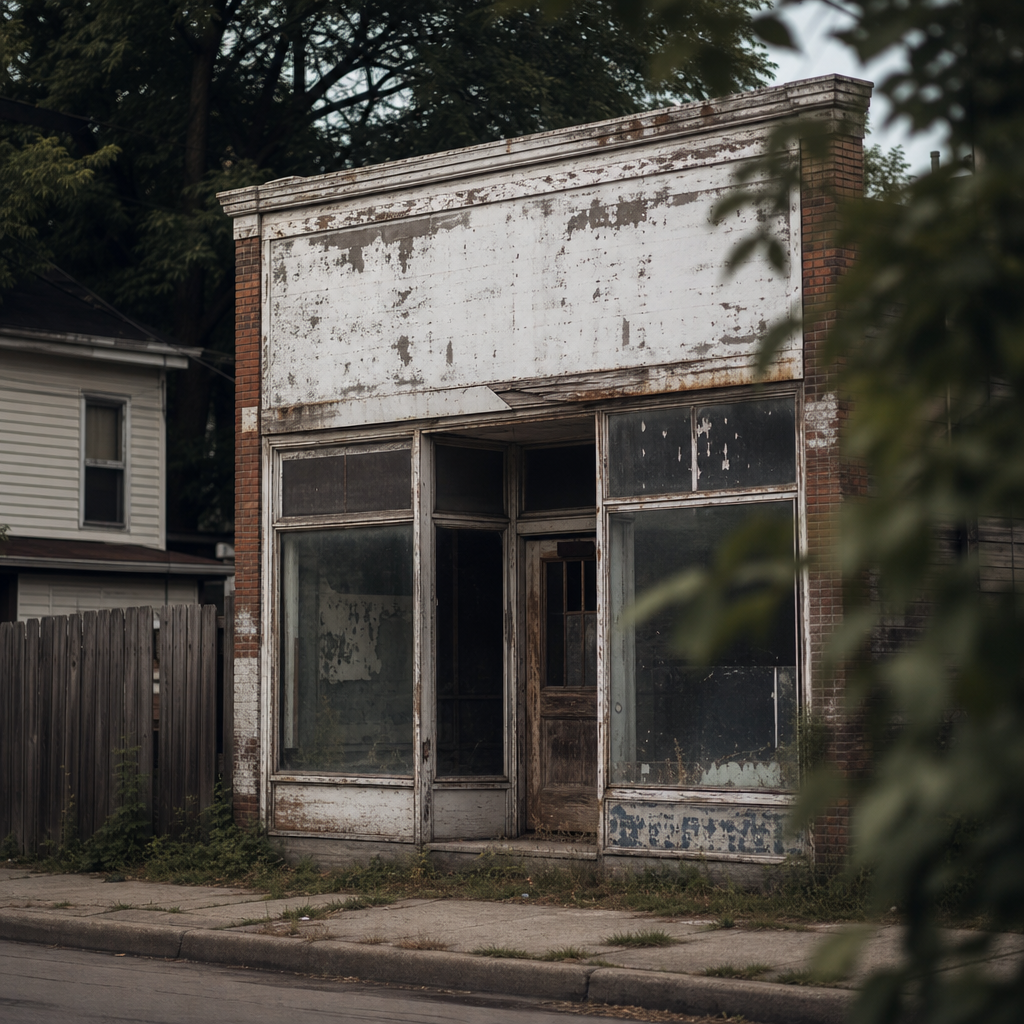
There's a building in almost every old town centre that most people under forty have never been inside. It might be a Greggs now, or a vape shop, or just a padlocked unit with a faded fascia. But if you look at the brickwork above the door, or the tiling round the step, you can sometimes still read what it used to be: a post office, a building society branch, a credit union. The kind of place where, on a Saturday morning in the 1970s, a parent would bring a child to the counter and hand over a few pounds in cash, and a person on the other side would stamp a little book.
That stamping was not just admin. It was an education.
The Infrastructure Nobody Noticed Was Teaching You
The savings habit – the one people tell you is just about willpower and discipline – was never really about willpower and discipline. It was about proximity. If you grew up in a street within walking distance of a post office savings counter, or a building society that your parents used, or a workplace credit union, you absorbed a mental model for money that a child three postcodes away simply never got. Not because they were less intelligent or less responsible. Because the building wasn't there.
Credit unions in particular worked like this. They were neighbourhood institutions, often attached to a particular factory, church, or community. You became a member before you became a borrower. The whole structure quietly rewired how money felt – not as something that arrived and disappeared, but as something you moved deliberately, in one direction, on purpose. The act of going in and depositing taught the idea as much as the deposit itself did.
Why did building society branches disappear from British high streets?
Then, from the mid-eighties onwards, those buildings started vanishing. Building societies merged, demutualised, became banks, moved online. Post office savings quietly shrank into the background. Credit unions, still often brilliant where they survive, became invisible in towns where they'd never been strong.
The people who already had the habit kept it, because the habit was by then inside them. But the next generation in those streets – the one that would have learned it by going along on a Saturday – learned nothing. There was nowhere to go.
For an honest, unsponsored look at how money decisions land differently depending on where you grew up, The Only Honest Review of a Luxury Holiday Comes From Someone Who Can't Read at savingourplanet.co.uk is worth an afternoon.
"Just Put Something Aside Each Month"
This is why that phrase – friendly, cheerful, perfectly correct – lands so differently depending on who hears it. If you grew up in a household where saving was a routine with a physical location attached, the advice makes sense immediately. You have a template. You know what the habit feels like from the inside.
If you didn't, the advice is a bit like being told to cook from scratch when you've never seen a kitchen. The instruction isn't wrong. The infrastructure is just missing.
The good news is that the infrastructure can be rebuilt privately. A standing order set up on payday, going to an account you don't look at daily, is about as close as most people can get now to the old stamped book. It's not as good – nobody hands it back to you and says well done – but the principle holds. Remove the decision. Automate the movement. And the habit has somewhere to live.
The question was never whether people wanted to save. It was whether anyone had ever shown them where to put it.
Questions this raises
- Can you still get a passbook savings account in the UK?
- Does a savings app teach children the same habit?
- What replaced the Post Office savings stamp book?